September 29, 2026 · 5 min read
A 4x ROAS Can Still Be Too Expensive: Build a Contribution Budget
Calculate an affordable acquisition cost from net sales, variable costs and required contribution, with a worked retail and lead-generation example.
By the AdvisorPPC Team · Reviewed by Claude
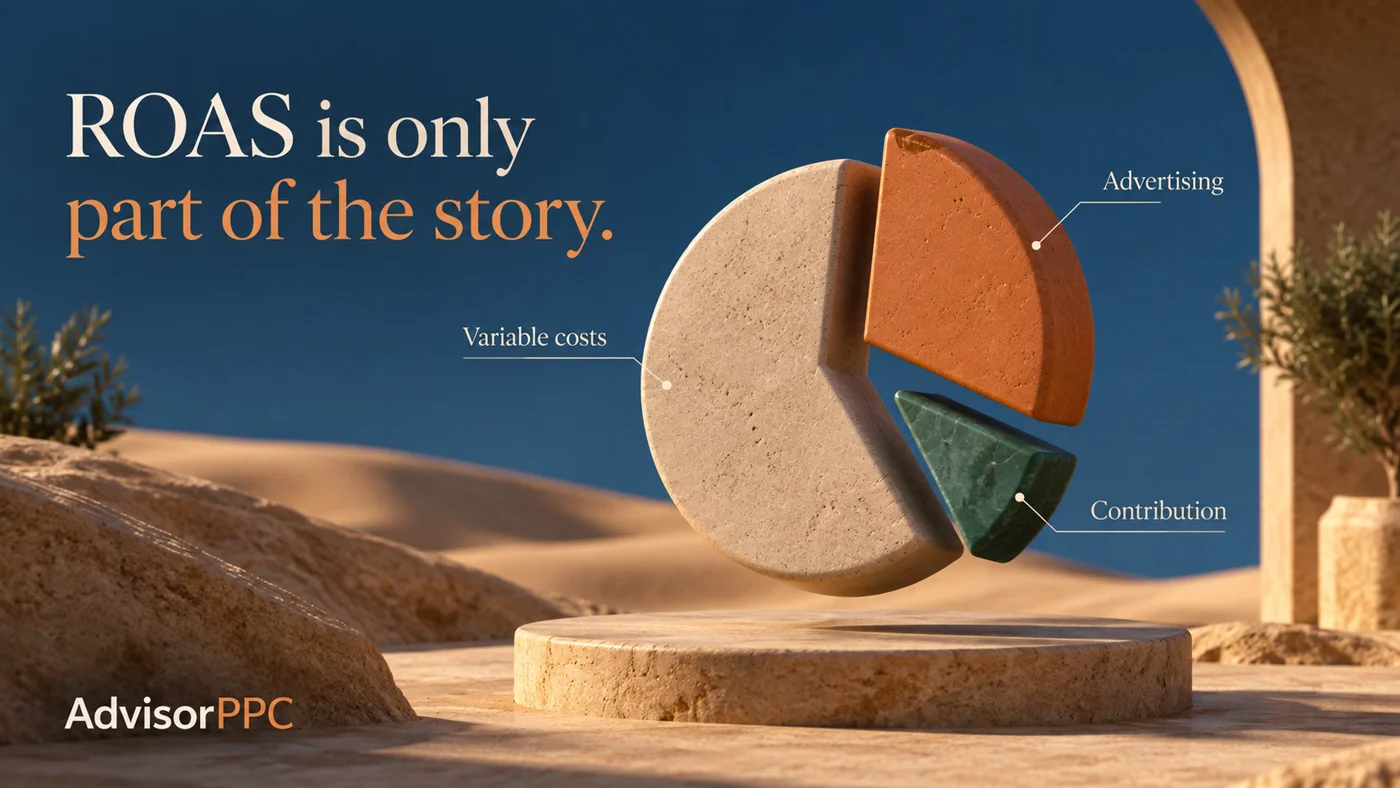
Return on ad spend answers a narrow question: how much attributed conversion value appears for each unit of advertising cost? It does not automatically tell you how much money the business keeps. An owner deciding whether to raise spend needs to connect that ratio to product costs, fulfillment, refunds and the contribution required to run the business.
Start by writing down what the reported value represents. It might be order revenue, a fixed amount assigned to each inquiry, or an estimate of profit. Google Ads allows conversion values to represent different business outcomes, so the label alone is insufficient. About conversion values.
Establish the economic unit
Choose a paid order, completed booking or acquired customer. Keep that unit consistent across the worksheet. For a retailer, calculate net sales after discounts and refunds, excluding pass-through amounts that are not economic revenue for this analysis. Ask your finance owner to confirm the treatment of taxes, shipping and fees.
Then list variable costs incurred because the order exists: product cost, fulfillment, packaging, payment processing, sales commission and incremental service labor where applicable. Avoid subtracting the same cost twice. If a refund adjustment already reduces net sales, do not subtract the refunded sale again as a variable expense.
This is a managerial planning worksheet, not a replacement for formal accounting. Its purpose is to make the acquisition decision internally consistent.
Work through a hypothetical month
Suppose a retailer records 100 attributable paid orders averaging $120 in net sales. Total net sales are $12,000. Variable costs average $72 per order, leaving $48 per order before advertising, or $4,800 in total.
Advertising cost is $3,000. Revenue ROAS is $12,000 divided by $3,000, which equals 4.0. After advertising, the cohort contributes $1,800 toward overhead and profit. If $1,000 of fixed overhead is allocated to this activity for the decision, $800 remains under these assumptions.
Now imagine a different product mix with variable costs of $96 per order. Revenue and ROAS remain unchanged, but pre-advertising contribution falls to $2,400. After the same $3,000 ad cost, the cohort loses $600 before fixed overhead. A 4x revenue ratio describes both scenarios equally well.
That is why your target cannot come from another business's screenshot. The product mix and costs behind its revenue may be completely different.
Calculate a floor and an operating target
In the first scenario, the contribution margin before ads is 40%: $48 divided by $120. A revenue ROAS of 2.5 would spend all that contribution on advertising because one divided by 0.40 equals 2.5. That is a break-even point before fixed overhead and profit, not a desirable operating target.
Suppose you want to preserve $18 per order after acquisition. The affordable advertising cost per order is $48 minus $18, or $30. At $120 net sales, the corresponding revenue ROAS target is 4.0.
Use these formulas:
Affordable acquisition cost = contribution before acquisition - required contribution after acquisition
Revenue ROAS target = net sales per order / affordable acquisition cost
If the affordable cost is zero or negative, the offer cannot support paid acquisition under those assumptions. Changing a bidding setting does not repair that arithmetic.
The value-based bidding guide explains why better values matter. Before using them, check whether reporting includes duplicate or differently counted conversions.
Translate the target into lead economics
A service business may pay for leads rather than immediate orders. Suppose a completed job contributes $240 before acquisition, and the business wants to retain $120. Its affordable acquisition cost is $120 per paid job.
If one in five qualified leads becomes a paid job, the expected affordable cost per qualified lead is $24: $120 multiplied by 20%. That is a planning estimate. It assumes comparable leads, a stable close rate and a mature observation period. Raw form submissions need a separate qualification rate.
If only half of submitted forms qualify, the expected affordable cost per raw form falls to $12. This makes the business case for checking lead quality before celebrating a lower platform cost per conversion.
Test the assumptions that could reverse the decision
Build three cases for refund rate, average order value, variable cost and lead-to-sale rate. Do not change every assumption in the favorable direction and call the result a forecast. Identify the one or two uncertain inputs that matter most and assign someone to reconcile them.
Also distinguish attributed and additional sales. Google describes Conversion Lift as a controlled approach to assessing advertising's causal effect, with account availability constraints. A revenue dashboard alone cannot establish that every attributed order would disappear without advertising. About Conversion Lift.
Your cash horizon matters too. A plausible annual customer value does not mean a new business can finance six months of acquisition costs today. Begin with observed contribution over a period your cash reserves can support, then show future value separately.
Take one decision to your next review
Complete a row for each major product or service: net revenue, variable cost, contribution, required retained contribution, affordable acquisition cost and evidence date. Flag any row whose costs or refund assumptions are missing. Compare the resulting target with actual mature cohorts before choosing between target CPA and target ROAS.
Use AdvisorPPC's current plans to evaluate which reporting and editing access fits that review. The useful outcome is a spending decision grounded in your economics. A high ratio becomes valuable when it leaves enough contribution for the business you intend to build.